Should One Parent Stay Home? A Financial Framework for the Decision
Beyond the simple "salary minus childcare" calculation: understanding the true financial impact of having one parent leave the workforce.
The decision of whether one parent should stay home to care for children is deeply personal, involving values, career aspirations, and family dynamics that go far beyond finances. However, understanding the true financial picture is essential for making an informed choice.
Many families make a simple calculation: if childcare costs more than one salary, staying home "makes sense." This approach dramatically oversimplifies the math and ignores several major factors that affect long-term household finances.
The Common Mistake: Simple Salary Comparison
Here's the calculation many families make:
Incomplete Calculation (Don't Do This)
Lower-earning parent's salary: $55,000
Full-time daycare for 2 kids: $36,000
"Net benefit" of working: $19,000
This calculation ignores taxes, benefits, and long-term career impact.
The Complete Financial Picture
A thorough analysis should include all of these factors:
Income-Related Factors
- Gross salary - The starting point, but not the whole picture
- Health insurance value - If both parents have employer coverage, losing one policy may require buying more expensive coverage or losing a backup option
- Retirement contributions - Employer 401(k) matches, pension contributions, and your own contributions stop immediately
- Other benefits - Life insurance, disability insurance, FSA/HSA employer contributions, tuition assistance
Stay-at-Home Parent Essentials
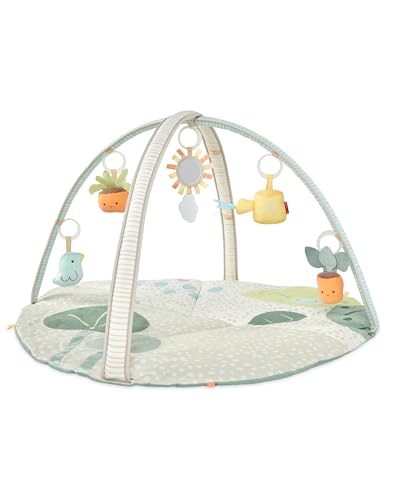
Best Play Gym for Tummy Time
Best OverallConverts from tummy-time mat to sitting play gym, so it stays useful from newborn through toddling rather than being outgrown in a season.
View on Amazon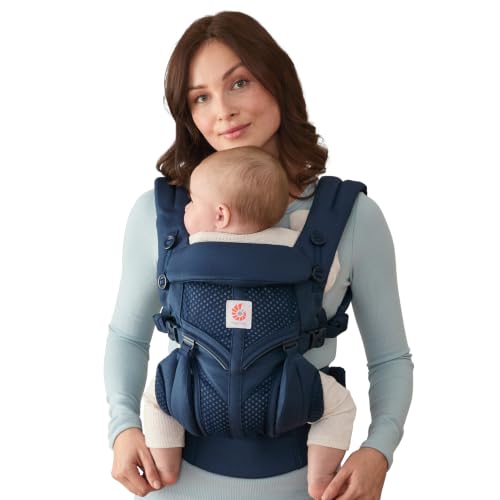
Best Baby Carrier
Best OverallCovers newborn to toddler without an infant insert, which is the thing that makes cheaper carriers a short-lived purchase.
View on Amazon
Best Baby Gate
Best for StairsHardware-mount option makes it safe at the top of stairs, and it adapts to awkward openings most gates will not fit.
View on AmazonTax Considerations
- Combined tax bracket - The working parent's income is taxed at higher marginal rates; the staying-home parent's income may have been partially taxed at lower rates
- Dependent Care FSA - You lose access to this pre-tax benefit ($7,500/year for 2026, per IRS Publication 15-B) if neither parent has earned income
- Child and Dependent Care Credit - This tax credit (up to $1,050 for one child, $2,100 for two) is only available to families where both parents work or look for work
- Social Security credits - The stay-home parent stops accumulating work credits, affecting future benefits
Career Impact Factors
- Lost raises and promotions - Salary growth continues for employed workers; a gap means missing multiple raise cycles
- Skills depreciation - In fast-changing fields, a multi-year gap can make re-entry difficult
- Re-entry penalty - Studies show parents returning after career gaps often earn less than those who didn't leave
- Networking and professional development - Career relationships and certifications require maintenance
Long-Term Cost Example
A parent earning $60,000 who leaves the workforce for 5 years may face:
- • $300,000+ in lost wages during the gap
- • $50,000+ in lost employer retirement contributions
- • $15,000-30,000 lower salary upon return (re-entry penalty)
- • Reduced Social Security benefits in retirement
This doesn't mean staying home is the wrong choice, but the full costs should inform the decision.
A More Complete Calculation Framework
Here's a more thorough way to evaluate the financial tradeoffs:
Step-by-Step Analysis
1. Calculate True Take-Home Pay
Start with gross salary, subtract taxes at the marginal rate (not average rate), subtract commuting costs, work clothes, and other work-related expenses.
2. Add Benefits Value
Include employer 401(k) match, health insurance contribution (if you'd lose coverage), life/disability insurance, and any other employer-paid benefits.
3. Subtract Childcare Costs
Include all childcare: daycare, before/after school care, summer camps, and the portion of these paid with pre-tax dollars through FSA.
4. Factor in Tax Benefits Lost
Dependent Care FSA savings, Child and Dependent Care Credit, potential loss of some deductions if filing status changes.
5. Estimate Long-Term Career Impact
This is harder to quantify but crucial. Consider your field's tolerance for gaps, your expected career trajectory, and realistic re-entry scenarios.
Planning Considerations
Cash Flow Impact
The immediate cash flow impact may be smaller than the simple salary-vs-childcare calculation suggests once you factor in taxes, benefits, and work expenses. Calculate your actual monthly difference, not theoretical annual savings.
Time Tradeoffs
Working parents face time constraints, but stay-home parents face isolation risks and the challenge of re-entering the workforce. Consider whether part-time work, flexible schedules, or remote work could provide a middle ground.
Long-Term Impact
The financial impact extends decades into the future through compound effects on salary growth, retirement savings, and Social Security. A 5-year career gap at age 32 can reduce lifetime earnings by $500,000 or more in some professions.
When Staying Home May Make More Financial Sense
- Multiple children in full-time care simultaneously
- Child with special needs requiring specialized or full-time parental attention
- Career with easy re-entry (teaching, healthcare, certain trades)
- Very high childcare costs relative to income (expensive metro areas)
- One parent's income is already very low with limited growth potential
When Continuing Work May Make More Financial Sense
- Career with strong salary growth trajectory
- Field where gaps significantly hurt re-entry prospects (tech, finance, law)
- Valuable employer benefits (pension, generous 401k match, stock options)
- Only one child, limiting total childcare costs
- Access to affordable childcare options (family help, employer subsidies)
Middle-Ground Options to Consider
The choice isn't necessarily binary. Consider these alternatives:
- Part-time work - Maintains career continuity while reducing childcare needs
- Remote work - May allow for some childcare flexibility and eliminate commute costs
- Shift work - Parents working opposite shifts can minimize outside childcare
- Freelance or consulting - Maintains professional connections with flexible hours
- Phased return - Some employers offer reduced schedules for parents of young children
Frequently Asked Questions
How long of a career gap is "too long"?
This varies by industry. In fast-changing fields like technology, even 2-3 years can be challenging. In education, healthcare, or skilled trades, gaps of 5+ years may be more manageable with refresher training.
What about the value of a parent being home that can't be measured?
This is absolutely real and important. The financial analysis helps you understand the economic tradeoffs, but the final decision involves values and preferences that numbers can't capture.
Should we factor in divorce risk?
Financial advisors generally recommend both partners maintain some career continuity and financial independence. A stay-home parent's economic vulnerability increases with time out of the workforce.
Can a spousal IRA help offset retirement savings loss?
Yes, a working spouse can contribute to an IRA for a non-working spouse (up to $7,000/year in 2026). This helps but doesn't fully replace employer retirement benefits.
Calculate Your Childcare Costs
Start with accurate childcare cost estimates for your decision analysis.
Use the Daycare Cost Calculator